
If the company makes a trading loss — or has losses left over from earlier years — the Losses section of Corp Tax Calculations is where they're recorded and used. It opens with a movement table that shows what happened to the losses this period, followed by the inputs that drive it.
The loss movement
The table runs from the profit or loss per accounts to the tax-adjusted trading profit or loss — the accounts figure after add-backs (depreciation, disallowables) and capital allowances. That adjusted figure, not the accounts figure, decides whether a loss arises for tax, and the section says so when the two disagree: an accounts loss can still be a taxable profit once depreciation is added back, and an accounts profit can become a tax loss when capital allowances exceed depreciation. Beneath it the table lists losses brought forward, the amounts used this period, any loss arising, carry-back, and the balance carried forward. Each line carries a chip naming the CT600 box it feeds.
The inputs
- Trading Loss B/F (pre 1 April 2017) — the part of the brought-forward pool that arose before 1 April 2017. Older losses can only be set against profits of the same trade, so this figure feeds box 160. Leave it at zero unless the company has genuinely old losses.
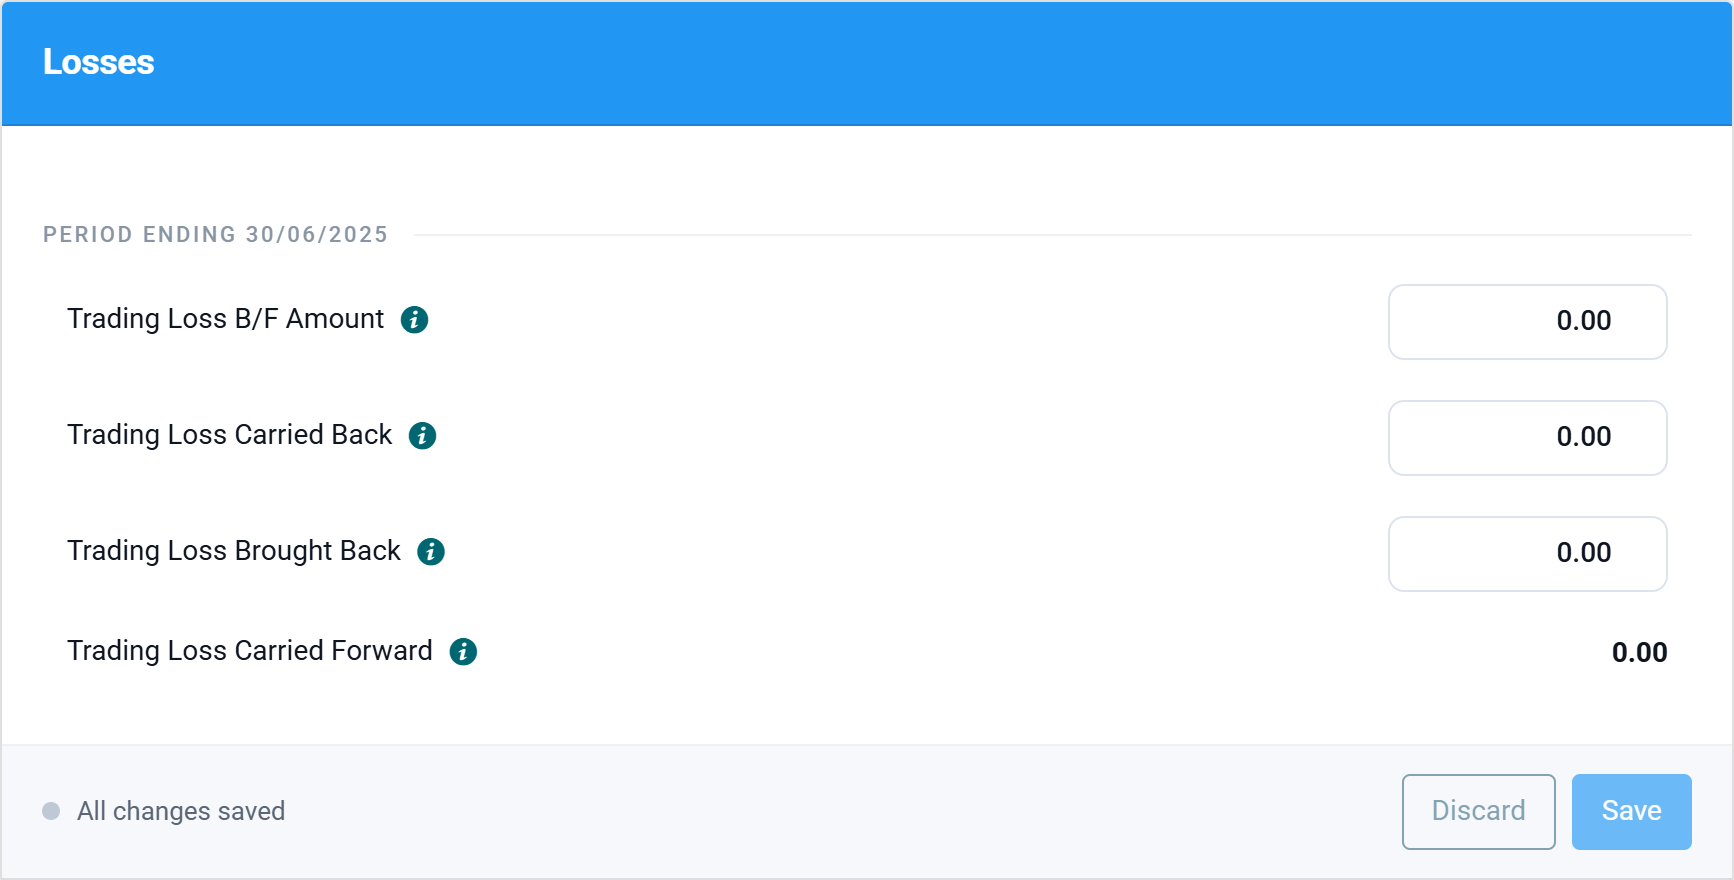
- Trading Loss B/F Amount — post-2017 losses brought forward from earlier periods. These are set against the period's total profits automatically and the amount used goes in box 285; whatever is not used rolls forward again.
- Trading Loss Carried Back — if this period made a loss, the amount you are electing to carry back against the previous year's profits (normally up to twelve months). Carrying back generates a repayment of tax already paid, so it is usually claimed before carrying forward. It ticks box 45, the claim affecting an earlier period.
- Trading Loss Brought Back — a loss arriving into this period from a later loss-making year's carry-back claim, reported in boxes 275 and 280. You would normally enter this when amending a period after a later year's claim.
- Trading Loss Carried Forward — calculated for you: whatever is left after current-year use and any carry-back, available to the next period.
Only the amounts actually used appear on the CT600 (boxes 160 and 285) — the form has no box for the pool itself. The unused balance carries forward automatically and is shown in the computation's Losses and Carried Forward Amounts schedules.
Long periods
When the accounts run longer than twelve months the return is split into two periods and the section gains a second block. Period 2 is a separate accounting period, so it can bring forward the loss Period 1 leaves behind: enter the amount to use in Trading Loss Brought Forward (from Period 1) (capped at Period 1's carried-forward figure) and the section shows what is set against Period 2's profits and what remains.
UK property business losses
A loss on the company's rental property is not a trading loss and has its own relief. The UK property business losses part of the section shows the property result for the period, any loss arising (box 805), the amount set against total profits (box 250) and the balance carried forward, with a single input for property losses brought forward from earlier years. How to mark rental income and letting costs as UK property, and how the relief works, is covered in UK property income and losses.
Non-trading loan relationship deficits
When the company's interest and other loan relationship debits exceed its credits, the excess is a non-trading deficit. The Non-trading loan relationship deficits part of the section shows the deficit arising this period (box 795), the amount set against total profits (box 260), any deficit brought forward and used (box 263), and the balance carried forward. Deficits arising this period come from the Non Trade Debit section; earlier years' unrelieved deficits go in Non-trade Deficit B/F. See Non-trading loan relationship debits and deficits for the detail.
Claiming the deficit before brought-forward property losses
Property losses (box 250) rank ahead of the deficit (box 260) on the CT600. So if the company has a large pool of property losses brought forward, that pool can use up all of this period's profits. Box 260 then shows a dash, and the whole deficit carries forward unused.
You don't have to use the brought-forward property losses first. A company can claim that some of its brought-forward property losses are not set against this period's profits (CTA 2010 s62), which leaves room to set this period's deficit against total profits instead (CTA 2009 s461). Whenever the period has a deficit arising and property losses brought forward, the section shows a tick box: Claim this period's deficit before brought-forward property losses. Tick it and:
- box 250 goes down by the amount of the deficit (or by all of the profits, if the deficit is bigger);
- box 260 goes up by the same amount, so the taxable profit doesn't change;
- the property losses held back are added to the property losses carried forward, so none are lost. A note under the tick box shows the amount, and the computation's UK Property Business schedule records the claim.
Only the brought-forward property losses are held back: a property loss arising in this period is always set against this period's profits in full. On a long period the claim applies to both return periods.
Worked example: property profit £8,696, a non-trading deficit of £6,910 and £59,925 of property losses brought forward. Without the claim, box 250 is £8,696, box 260 is nil and £6,910 of deficit carries forward. With the claim, box 250 is £1,786, box 260 is £6,910 and no deficit carries forward. The property losses carried forward go up by £6,910, from £51,229 to £58,139. The profit chargeable is nil either way. What changes is which relief is kept for later.
How the reliefs rank
Losses are applied in a fixed order in the profits-chargeable summary: pre-2017 trading losses against trading profit first, then property losses against total profits, then non-trading deficits (this period's, then brought forward), then post-2017 trading losses brought forward, and finally qualifying charitable donations — so each relief only sees the profit the earlier ones left. The tick box described above is the one way to change this order: it lets this period's deficit go ahead of brought-forward property losses. A current-period trading loss is set sideways against the period's other income (property profit, interest) before anything is carried back or forward. The relevant CT600 boxes are populated automatically, including the repayment boxes when a carry-back produces one, and the computation document shows the loss memo so you (or your accountant) can see exactly what was used, where, and what remains.
A profitable year like the example in this guide leaves the inputs at zero throughout — you only need them when losses exist.
Next: UK property income and losses, then Reviewing the computation, accounts and CT600.