Because the traditional Self Assessment channel has no HMRC calculation service, Tax Optimiser computes the full tax position itself — recalculated on every save, so the Calculation (SA302) section and the Total Tax Due card are never stale. The card spells out what the figure is: the amount due by 31 January including any first payment on account, or the repayment due when the client has overpaid, with the 31 January and 31 July instalments listed when payments on account apply.
Reading the calculation

The statement follows the same staged shape as HMRC’s SA302: income by type, deductions and the Personal Allowance (with the £100,000 taper where it applies), Income Tax by band, the reductions and non-repayable credits (trust and estate credits, non-resident and remitted dividend credits) that can only ever reduce the tax on their own income, Capital Gains Tax where the SA108 page is in use, pension savings charges and the Temporary Repatriation Facility charge where they apply, Class 4 and Class 2 National Insurance, student loan repayments, tax already deducted at source (PAYE, CIS, taxed interest, repayable credits), and finally the balancing payment and any payments on account for the following year with their due dates. Capital Gains Tax, pension charges and the TRF charge join the balancing payment but never the payments on account. Where basis period reform spreads a transition profit, its slice is shown on its own line so you can see what was left out of the High Income Child Benefit Charge.
PAYE coding adjustments and reducing payments on account
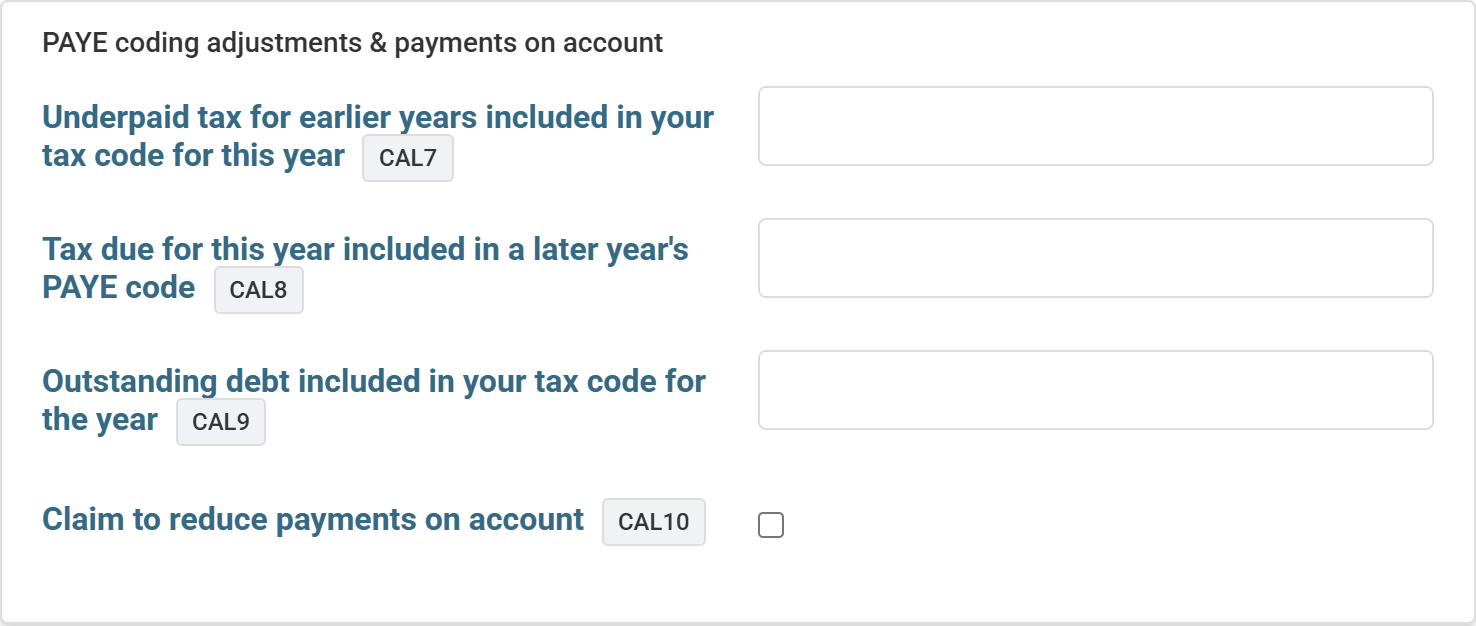
The card at the top of the Calculation section carries the SA110 boxes that adjust what is actually payable:
- Underpaid tax for earlier years in this year’s code and outstanding debt in the code — these add to the balancing payment, because that slice of the year’s PAYE was collecting old amounts, not this year’s tax. Take both from the client’s PAYE coding notice.
- Tax due for this year included in a later year’s code — this defers, reducing the balancing payment (it can bring it to zero but never create a repayment).
- Claim to reduce payments on account — tick the claim and enter the reduced first payment where next year’s income will be lower. The claim can only reduce: an amount at or above the calculated figure is ignored, with a note saying so.
How the tax was worked out
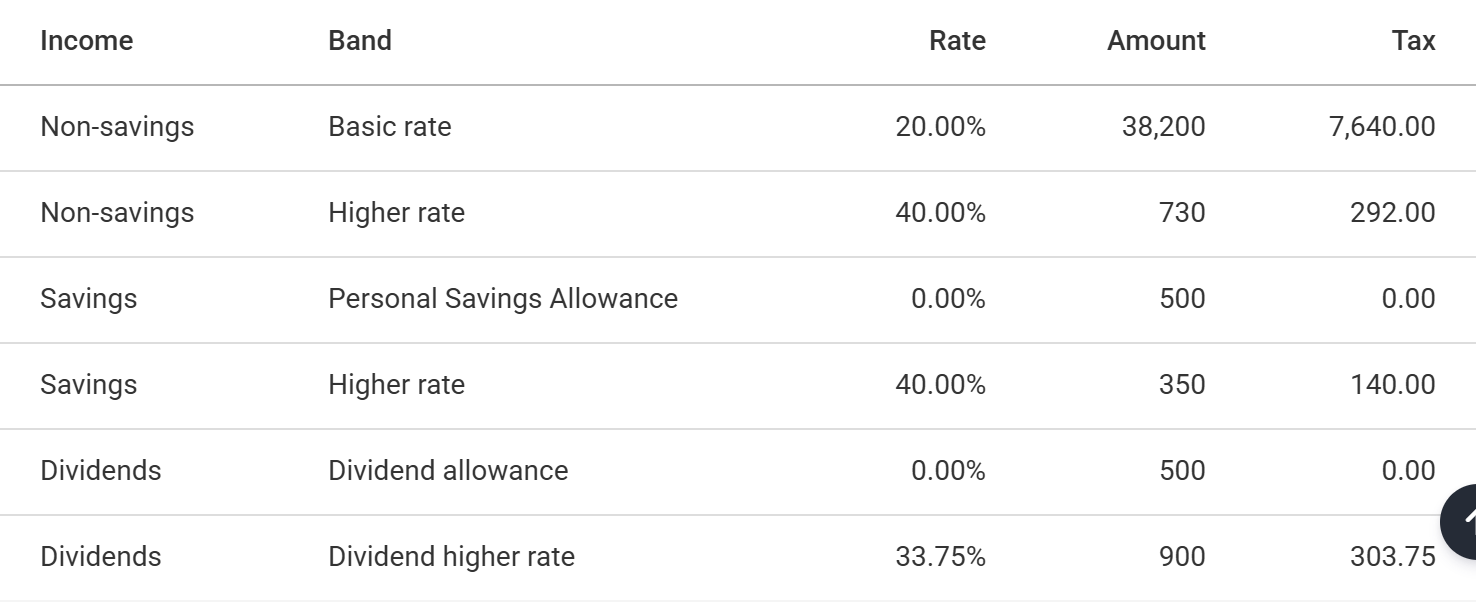
Below the statement, the band breakdown shows every slice of income against the band and rate that taxed it — including the 0% slices (Personal Savings Allowance, dividend allowance, savings starting rate) and any band extension from Gift Aid or pension contributions. Scottish taxpayers see the Scottish bands on non-savings income, with savings and dividends staying on UK-wide bands, exactly as HMRC applies them. Life-insurance gains and the pension annual allowance charge appear as top slices where they apply.
Carried forward to next year
When the year leaves something behind — a UK property loss, unused residential finance costs, unused finance costs from a partnership’s property share — a Carried forward to next year’s return table lists each amount with the box it goes into next year. Starting the next year from this one copies them into the new return.
Warnings: informational and blocking
The calculation flags anything it wants you to know about. Informational notes, in amber, explain a treatment or point at a chain of boxes that does not add up — how a state pension lump sum was taxed, that a non-repayable credit was capped, that the property boxes do not reach HMRC’s figure — and the section menu shows an amber count beside Calculation while any are outstanding. Blocking warnings, in red, mean the return cannot be filed online through Tax Optimiser, because it uses one of the two specialist areas the calculation does not yet cover; the menu count turns red. Where a warning belongs to a page, a Go to link beside it opens that page. A blocked return fails the pre-flight checks on the Submission screen, so nothing incomplete can reach HMRC by accident.
The SA302 PDF and the full return
Three buttons sit at the top of the section. Download SA302 PDF produces the tax-calculation document clients are asked for by mortgage lenders: the full statement, the band breakdown and the payments on account, over the client’s name and UTR. The PDF is recalculated from the saved figures at the moment you download it, and carries a draft banner until HMRC has accepted the return. Download full SA100 return PDF and Preview return give you the whole return on HMRC’s own forms — see the return on HMRC’s forms. As with any software calculation, it is advisory until HMRC processes the return — HMRC’s own figure is definitive.
Next: The return on HMRC’s forms.
