Partnerships with income beyond the trade report it on the SA800’s supplementary pages. The Supplementary step gathers all four on one screen; a page is only included in the submission when it actually carries figures, and the Review step lists which pages will go (“Supplementary pages with data”).
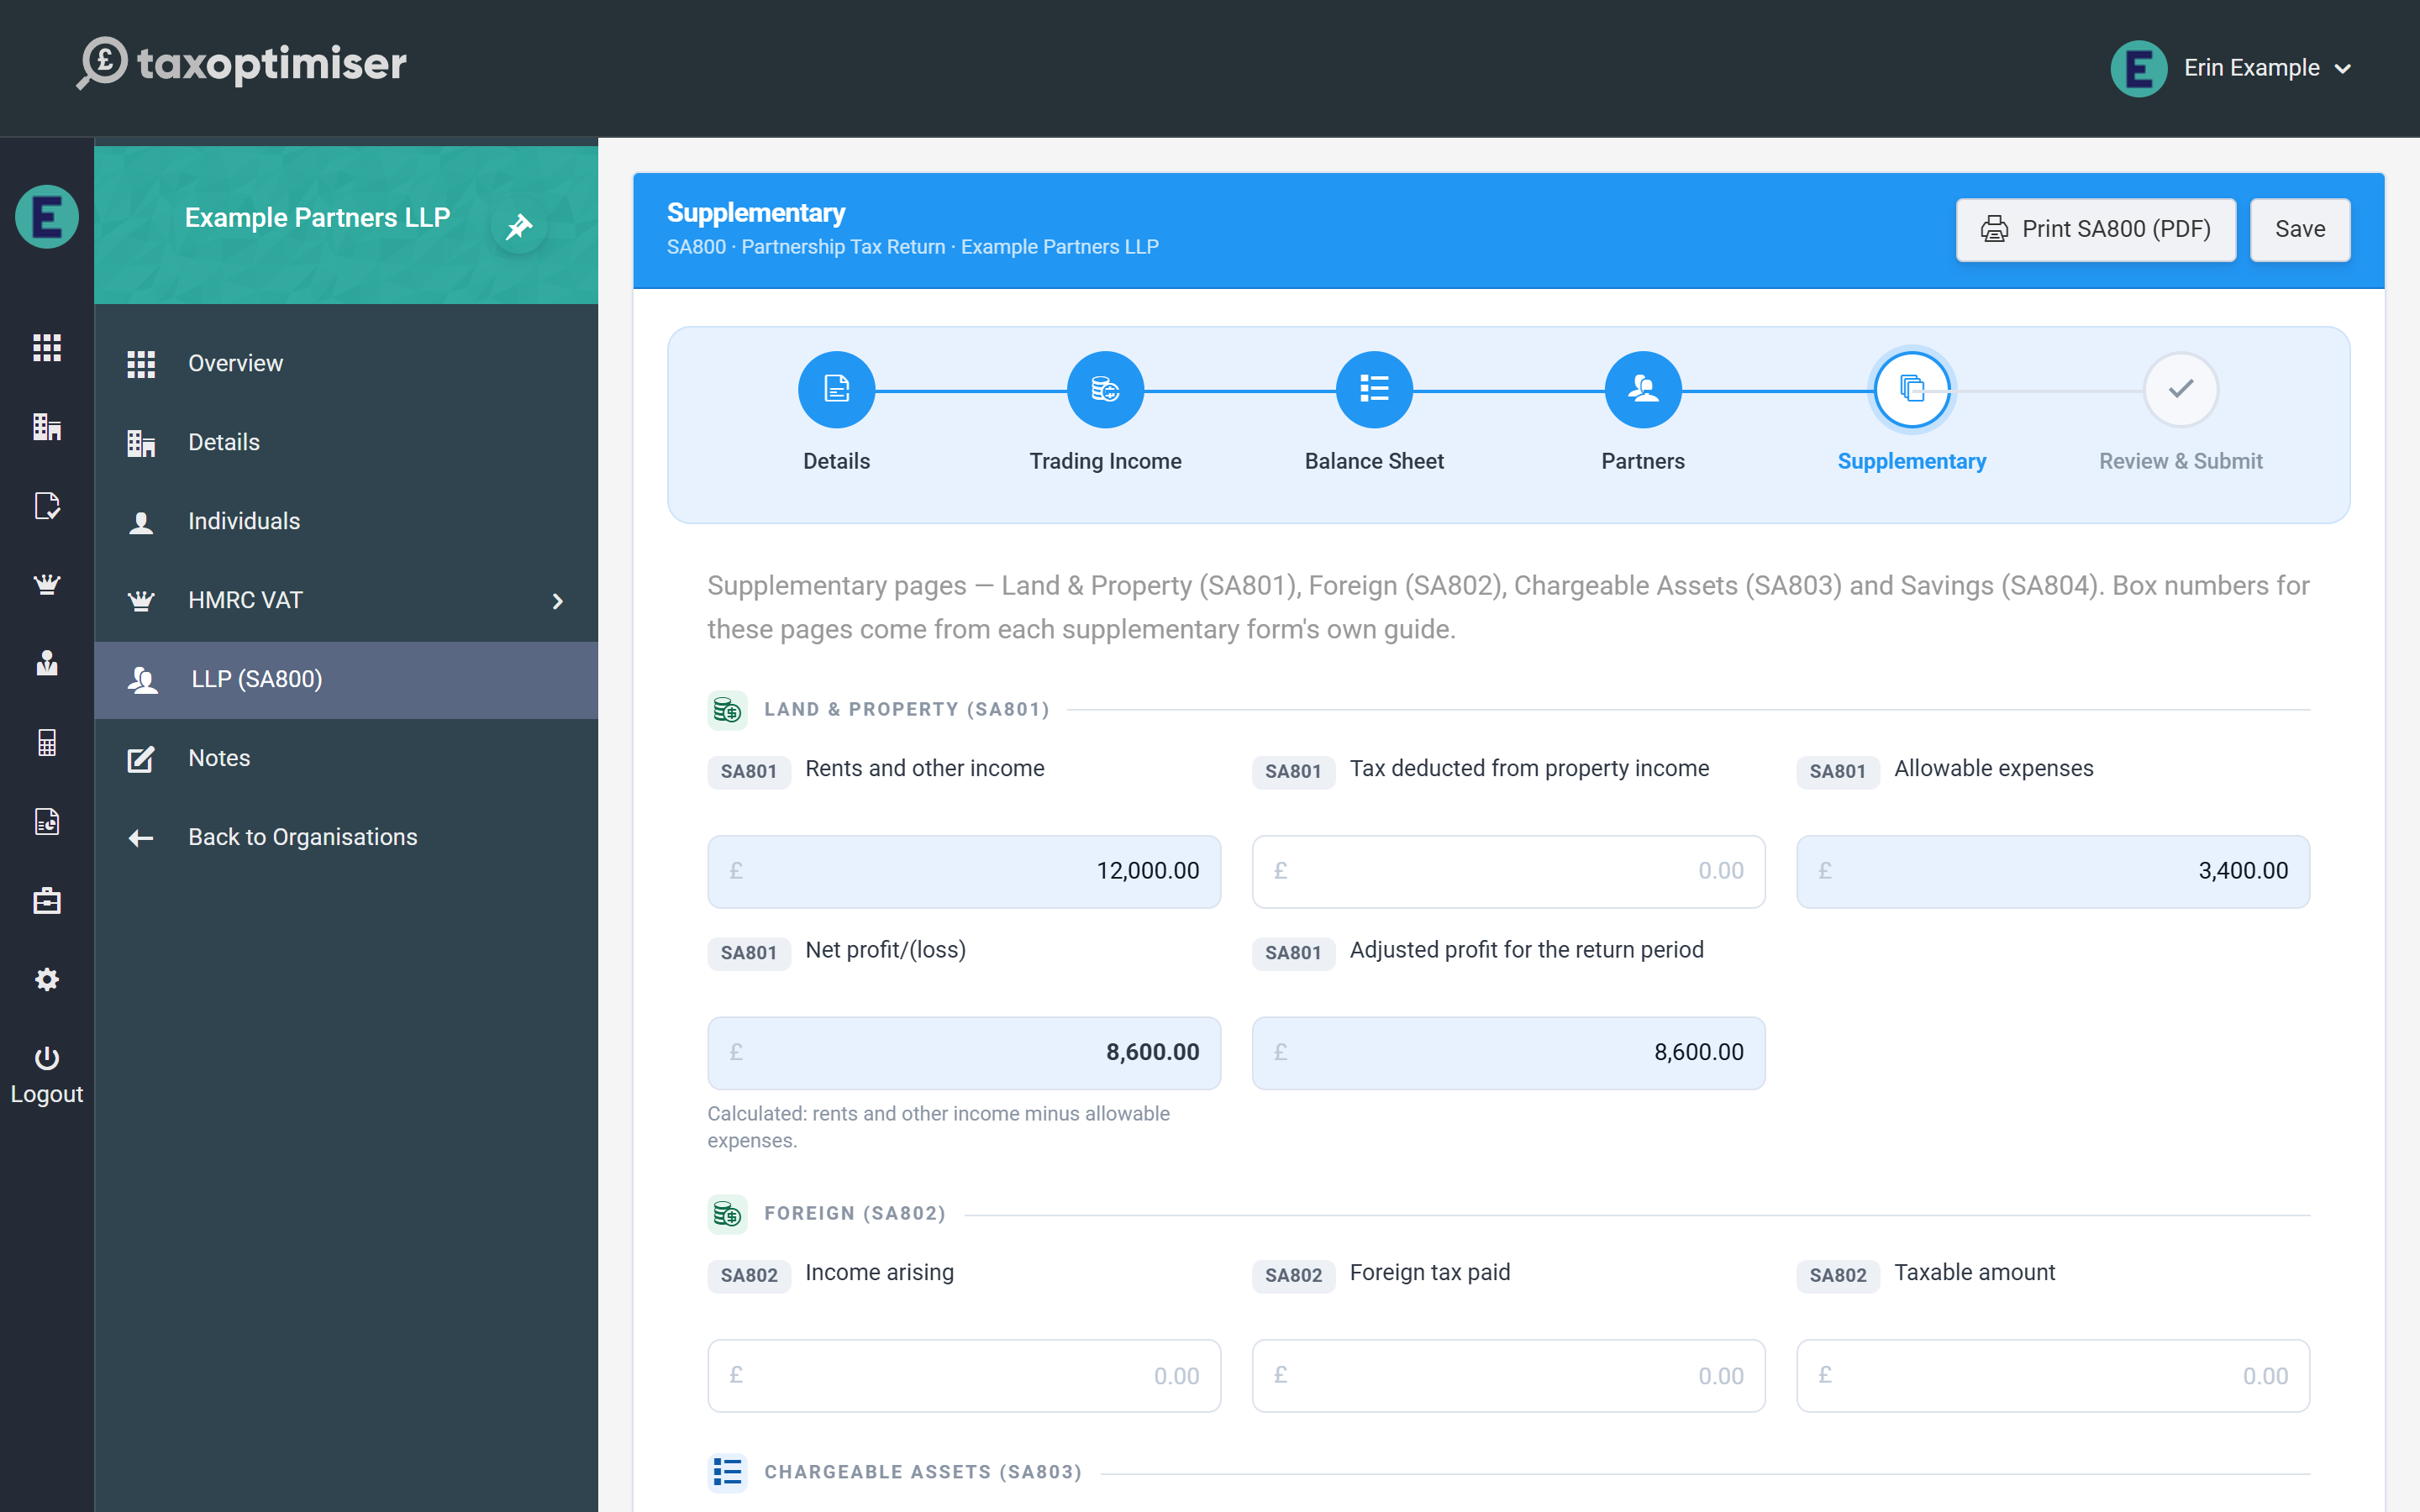
Every figure on these pages is carried to the Partnership Statement and shared between the partners by their profit share % on the Partners step — each box’s hint says which statement box it feeds.
Land & Property (SA801)
- Income: rents and other income (1.21), any tax deducted from it (1.22), chargeable premiums (1.23) and reverse premiums (1.23A).
- Expenses (1.25–1.30): rent, rates and insurance; repairs and maintenance; non-residential finance costs; legal and professional costs; cost of services provided; and other allowable expenses. Net profit/(loss) (1.32) is calculated.
- Tax adjustments: private use (1.33) and balancing charges (1.34) add back; the Annual Investment Allowance (1.35A), the other allowances (1.35B–1.36) and the cost of replacing domestic items (1.37) deduct. Profit/(loss) for the return period (1.39) is calculated from them and feeds statement box 19.
- Residential finance costs (1.40) — mortgage interest and similar costs on residential lets are not an expense. Enter them here and each partner receives their share in statement box 26 to claim the basic-rate tax reduction on their own return.
Under the grid, tick traditional (accruals) accounting (box 1.22A) if the property income is not on the cash basis — the Annual Investment Allowance on property can only be claimed with it.
Foreign (SA802)
Foreign savings income (rows 2.2) and foreign dividends (rows 2.2A) are entered one row per country — up to 20 of each — with the amount before foreign tax and the foreign tax paid. Tick Unremittable for income that can’t be brought to the UK: it is reported, but left out of the totals (2.6, 2.6A, 2.8) and the Partnership Statement. Foreign tax cannot be entered without the income it was paid on.


Land and property abroad: add a letting for each overseas let property (up to six), with its country, address, rents, expenses and tax adjustments — one SA802 page PF3 each. Several properties in the same country with no foreign tax can share one letting with “more than one property” ticked. The adjusted profit or loss of each letting is calculated; the remittable lettings are pooled into a taxable profit (copied to box 2.7 and statement box 17) or an allowable loss (box 2.10 and statement box 21). With more than one letting and a loss among them, enter each profitable letting’s amount chargeable after setting the loss against it — normally against the country with the lowest rate of foreign tax first. Residential finance costs go to box 2.10A and statement box 27. Chargeable premiums, offshore fund disposals (box 2.9 → statement box 18) and the traditional accounting tick (2.8A, needed once rents and balancing charges pass £150,000) sit under the lettings.


Chargeable Assets (SA803)

The partnership reports only the disposal proceeds from chargeable assets sold in the period. That is deliberate — a partnership isn’t itself chargeable to capital gains tax, so each partner computes their own gain or loss on their share via their personal return.
You can type a single total in box 4.1, or click Add disposal to list each asset with a description, a tick for unquoted shares, its proceeds and any further information (up to 50 rows, 80 characters each). Once disposals are listed, box 4.1 becomes their calculated total.
Savings (SA804)
- UK bank and building society interest (gross) — filed as untaxed interest unless you also enter tax deducted, in which case it is filed as taxed interest. HMRC requires the tax to be 20% of the gross, to within £1.
- National Savings & Investments interest (7.4).
- Dividends from UK companies and unit trusts, stock dividends and bonus issues (7.19–7.22).
- Other income: without tax deducted, as a profit (7.26) or a loss (7.27) but not both; or with tax deducted (7.30 gross and 7.29 tax, again 20%).
Like the main pages, anything the form derives is calculated read-only, and leaving a page untouched simply leaves it out of the filing — there is nothing to switch on or off.
