
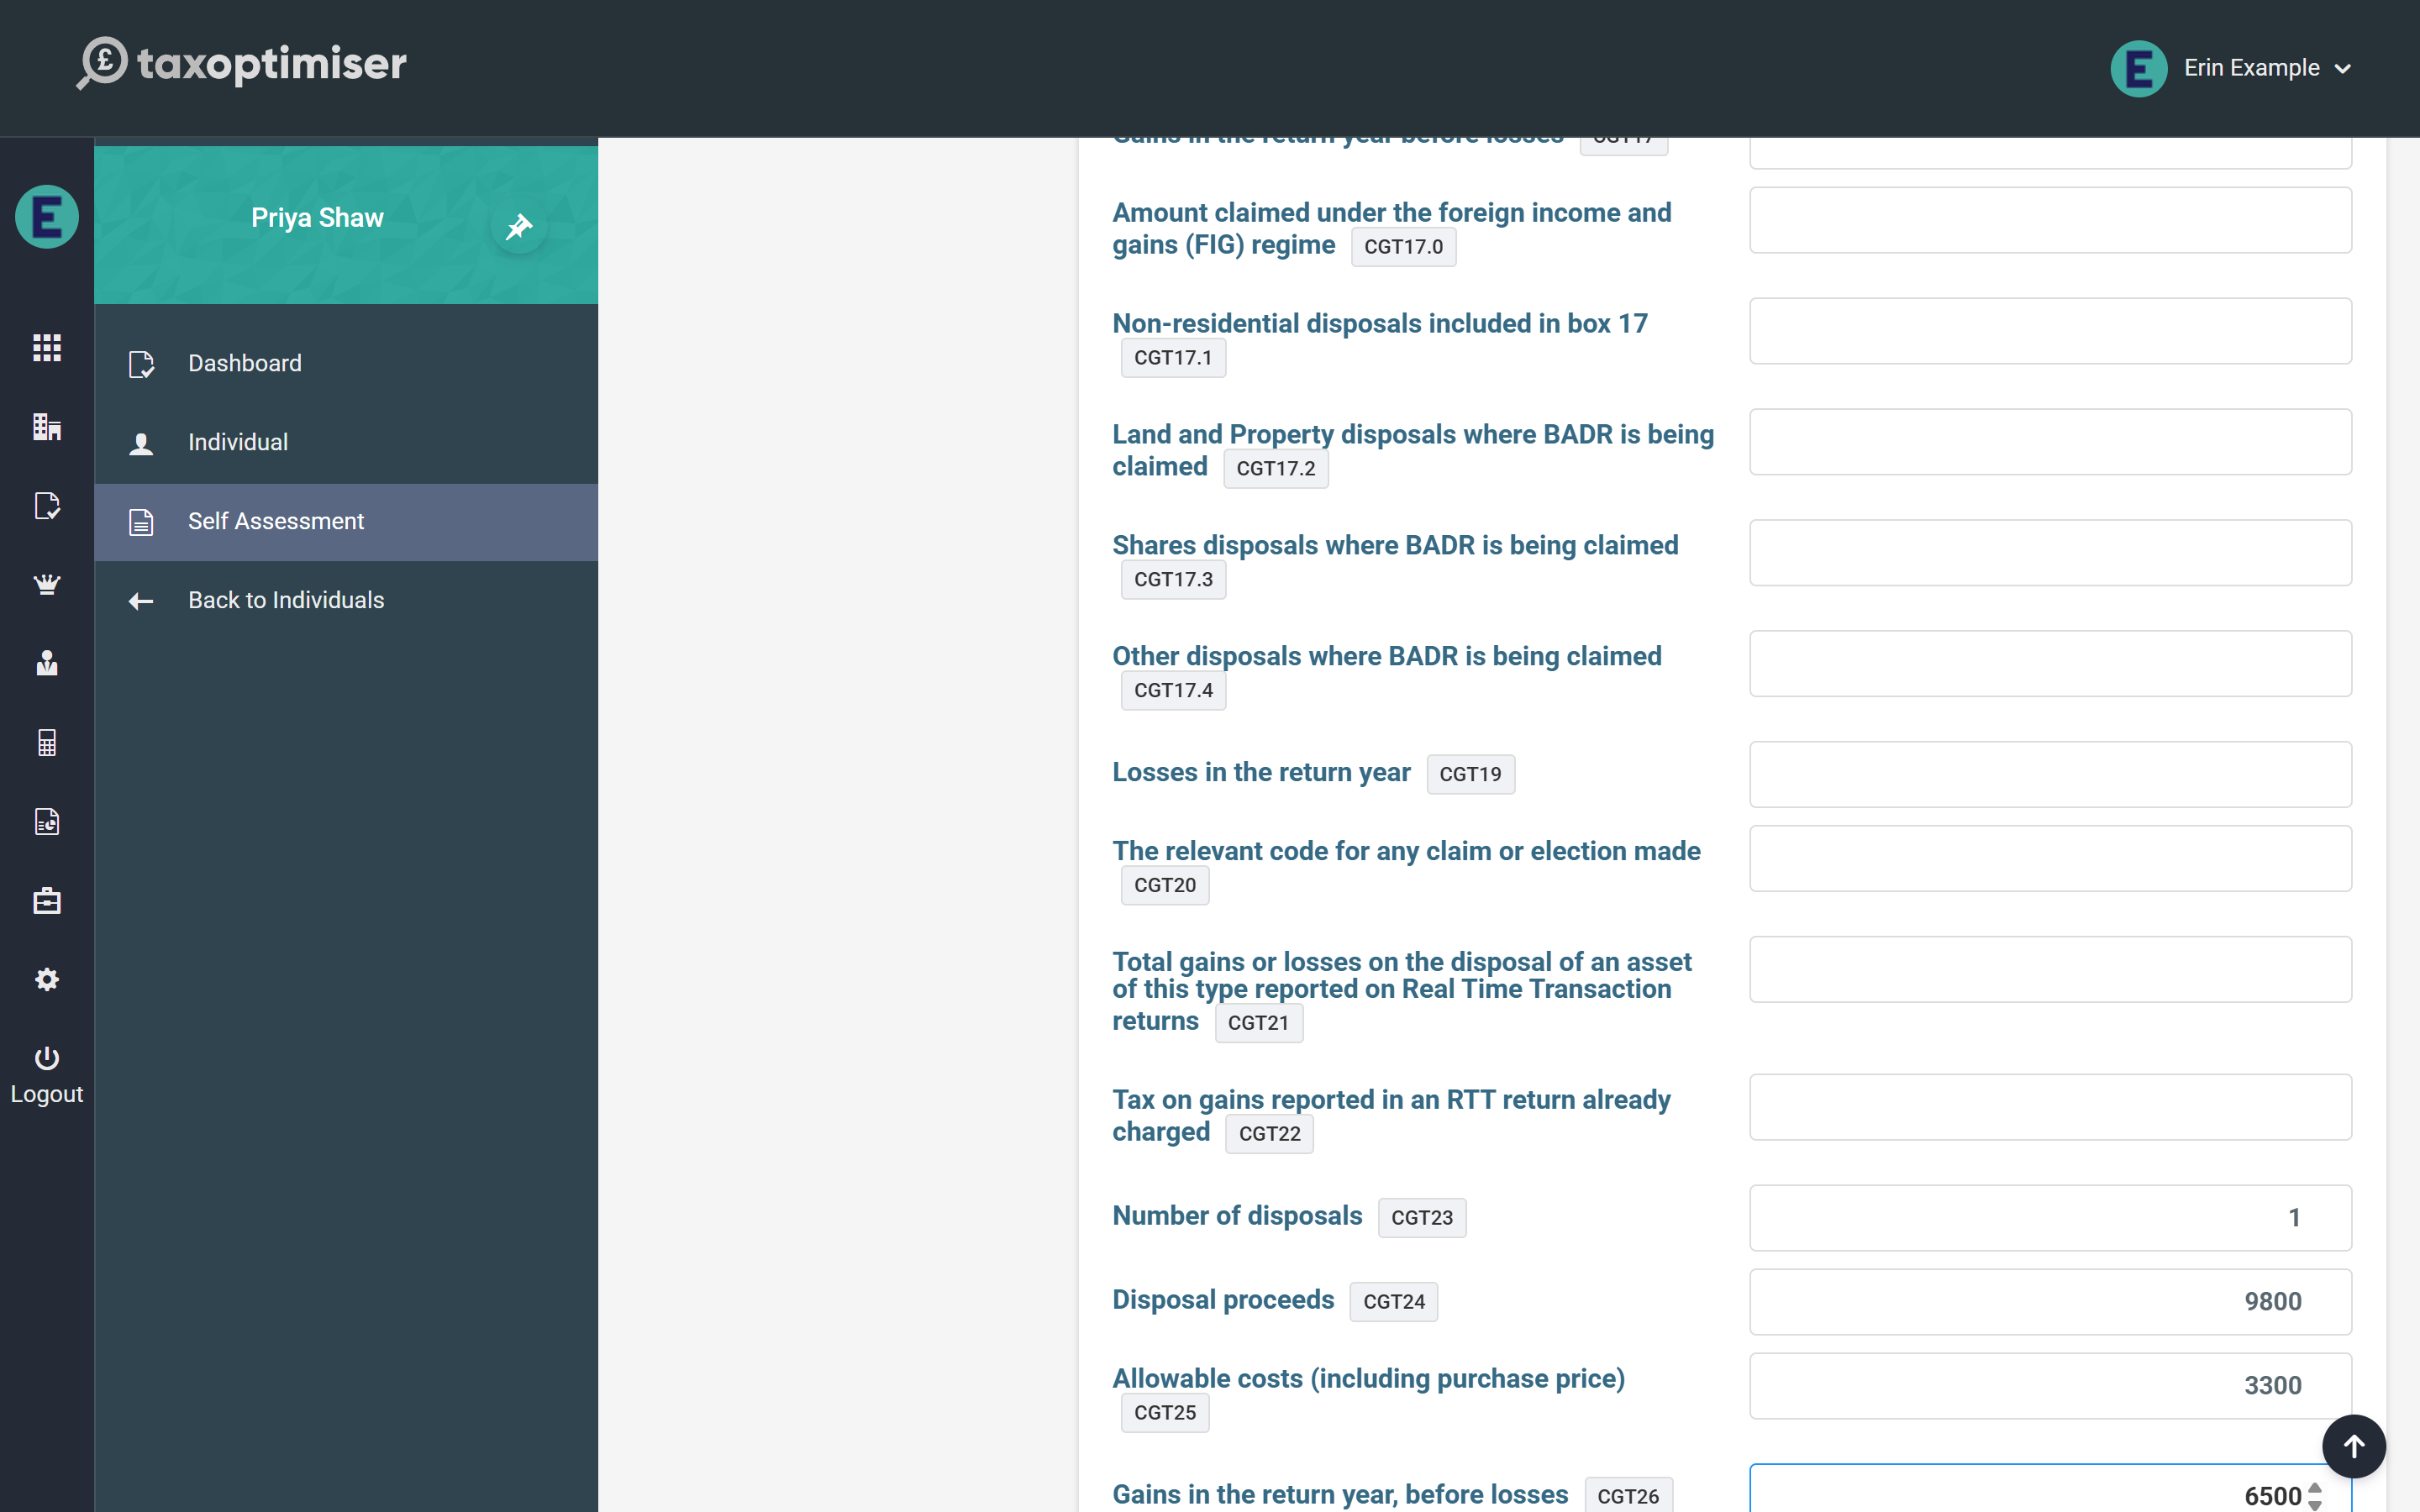
Enter the year’s totals per asset category — residential property, carried interest, listed shares and securities, unlisted shares, crypto-assets, other property and assets — with the disposal counts, proceeds, costs, gains and losses, exactly as on the paper SA108. Each category’s number of disposals is required by HMRC whenever its amount boxes are filled, and the hint under each count box says so.
How the tax is worked out
The calculation applies in-year and brought-forward losses and the £3,000 annual exempt amount in HMRC’s order — carried interest first, then residential property (including non-resident gains on UK residential property), then other gains, with Business Asset Disposal Relief gains last — and taxes what remains at 18% within any unused basic-rate band and 24% above it, with BADR and Investors’ Relief gains at their 2025-26 rate of 14% (18% for disposals from 6 April 2026) and carried interest at its own rate. The basic-rate band left for gains is measured against taxable income excluding any life-insurance gains beyond their annualised slice, as HMRC does.
Losses used only need to bring the gains down to the exempt amount (box 45), and the hint says so. Losses set against income (boxes 41 and 43) reduce the year’s income rather than the gains and together cannot exceed the unlisted-share losses in box 35.
Tax already paid
Capital Gains Tax already paid on UK Property (PPD) or real-time returns is credited against the CGT due. Where more was paid than the CGT now due, HMRC sets the excess against the Income Tax and National Insurance balance, and so does the calculation — shown on its own line of the statement — with only anything still left over not repaid through the return. Capital Gains Tax joins the balancing payment but never the payments on account.
Non-resident and other special gains
- Non-resident CGT (boxes 52.1 to 52.5) is a separate pool taxed on top of the main boxes in the band the main gains leave; a gain entered in both places would be taxed twice, and the calculation warns if it sees that. Box 52.5 losses come off it; any annual exempt amount left over is applied; box 52.4 is credited against the CGT due.
- BADR gains (box 50) must also be in box 17, split in boxes 17.2 to 17.4, with the lifetime total in box 50.1 (no more than £1,000,000). Investors’ Relief gains in box 49 cannot exceed box 34.
- Attributed gains, trust liabilities (box 52) and the QAHC boxes are information or added as keyed; box 48 is ignored by HMRC’s calculation and the hint says so.
- FTCR on foreign gains comes from box 39 of the Foreign page and reduces the CGT as keyed.
The computation HMRC insists on
HMRC will not accept a capital gains page without a summary of the computation. Put it in the Additional information box (box 54) at the foot of the page — a line per disposal with proceeds, costs and the gain is enough, plus the reference numbers of any UK Property or real-time returns — or attach the computation as a PDF in the Attachments card on the Submission section instead. Until one or the other is there, the pre-flight checks flag it and link straight back to this page.

Next: Residence, remittance basis and the FIG regime (SA109).
