
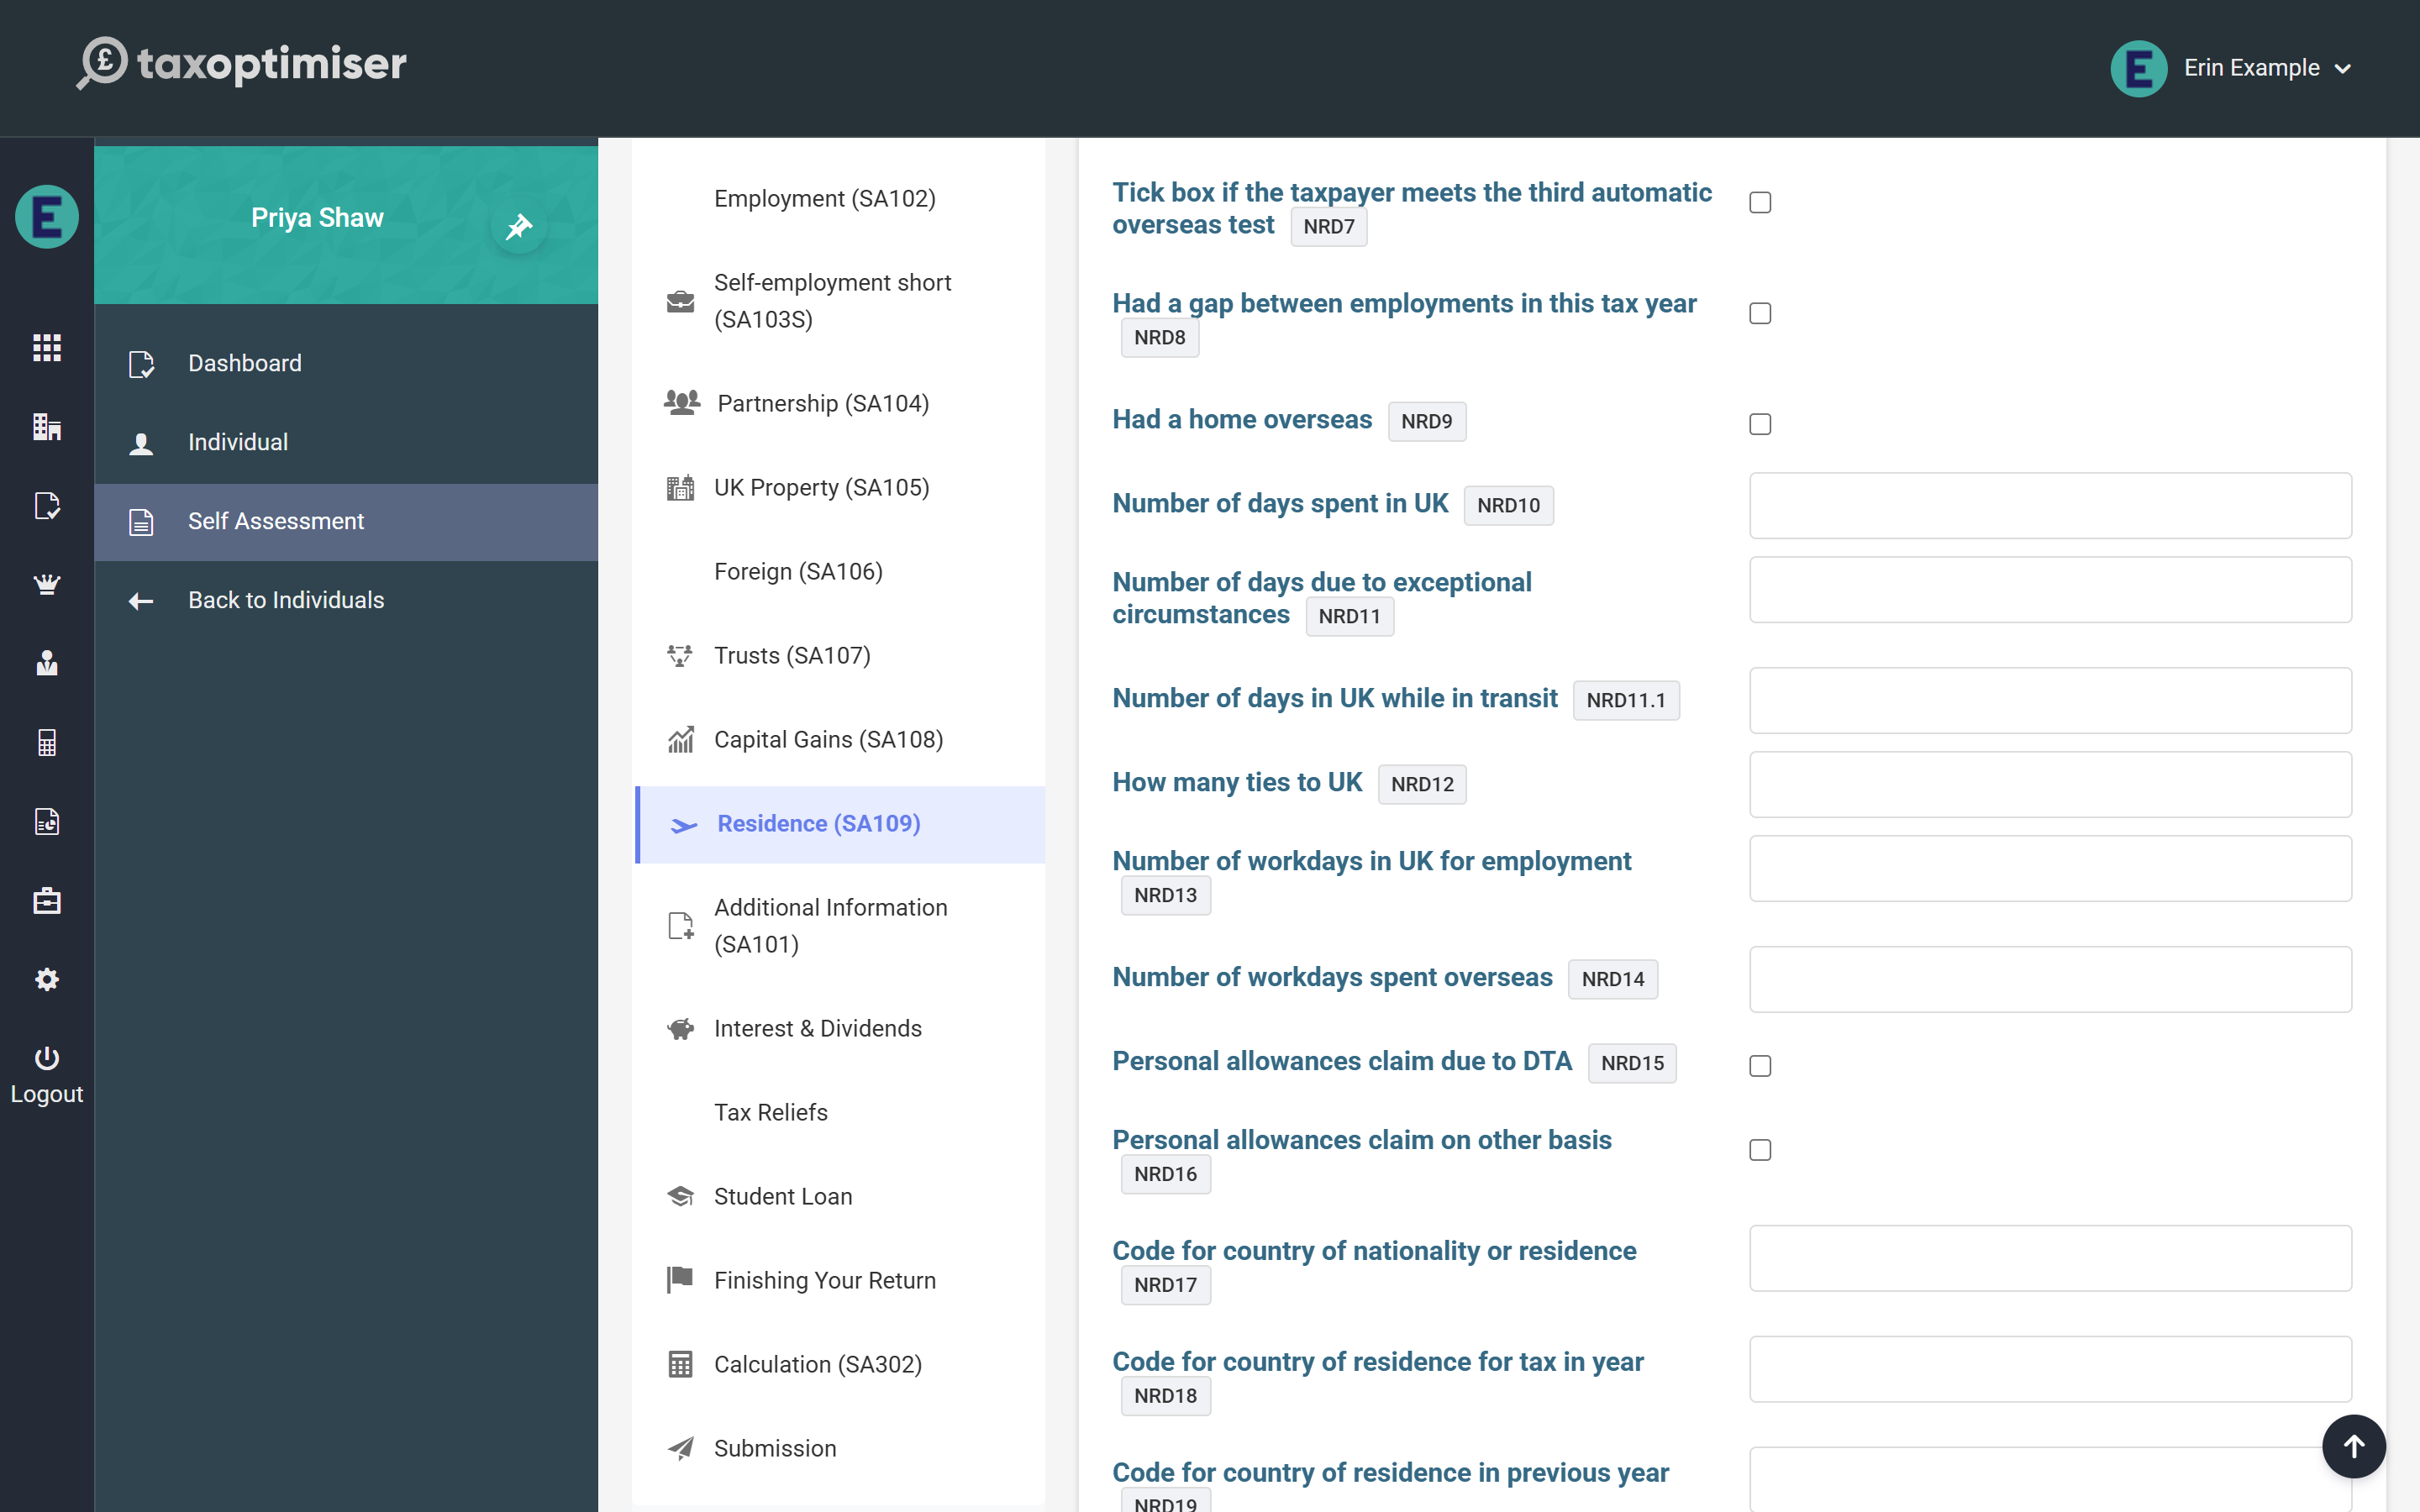
The Residence (SA109) page carries the statutory residence test entries — residence status, split-year treatment, day counts and ties — the personal allowance claims, the foreign income and gains (FIG) regime that replaced the remittance basis from 6 April 2025, Overseas Workday Relief, the Temporary Repatriation Facility and the double taxation claims. Every treatment on this page was confirmed against HMRC’s test service.
Non-residence and the Personal Allowance
A client marked not UK resident loses the Personal Allowance unless boxes 15 or 16 claim it (under a double taxation agreement or another basis), and the calculation shows a note whenever it has removed the allowance. A non-resident’s UK dividends — including dividend shares from trusts — carry a non-repayable credit at the dividend ordinary rate, which the calculation sets against the bill before tax deducted at source, exactly as HMRC does. Disregarded income rules are applied where they reduce the liability.
The FIG regime
A claim under the FIG regime (boxes 28 or 29, with the claimed amounts in the .1 boxes beside each foreign income or gains box on the Foreign, Capital Gains and partnership pages) takes the claimed income and gains out of charge. Any claim costs the Personal Allowance, Blind Person’s Allowance, Marriage Allowance received and the capital gains annual exempt amount; the savings allowance survives, and Class 4 is still charged on claimed trading profits. The calculation shows a note when a claim has removed the allowances. Each .1 claim can be no more than the box it sits beside, and the page checks that as you type.
Overseas Workday Relief and the Temporary Repatriation Facility
- Overseas Workday Relief (box 41) — the year’s total in box 49 comes off employment income after adjusted net income is measured, so the Personal Allowance taper uses the pay before relief; the Personal Allowance and exempt amount are kept. The transitional claim in box 43 works the same way. A box 40 election is treated as a FIG claim and costs the allowances.
- Temporary Repatriation Facility (boxes 50 to 53) — the designated amounts in boxes 51 and 52 are charged at a flat 12%, shown on its own line of the statement; the charge joins the balancing payment but not the payments on account.
The remittance basis for earlier years
Remittances of pre-April 2025 income and gains (the box 7.1 to 7.5 group on the Foreign page, with the remittance details here in boxes 34 to 39) are taxed as non-savings income; a company registration number in box 38 is required with any remittance box. Business Investment Relief entries are information only.
Double taxation relief
Relief claimed under a double taxation agreement in boxes 21 and 22 is a repayable credit taken exactly as keyed — HMRC does not cap it at the tax due and neither does the calculation — and it counts as tax deducted for the payments on account. Box 20 (the income relieved) is information only.
