
Choose short or full statements to match what the partnership issued — the short page when the Partnership Statement shows only a share of trading profit and bank interest, the full page for any other partnership income — and press Add Partnership for each one. A client can carry any number, each in its own card titled by the partnership’s name.
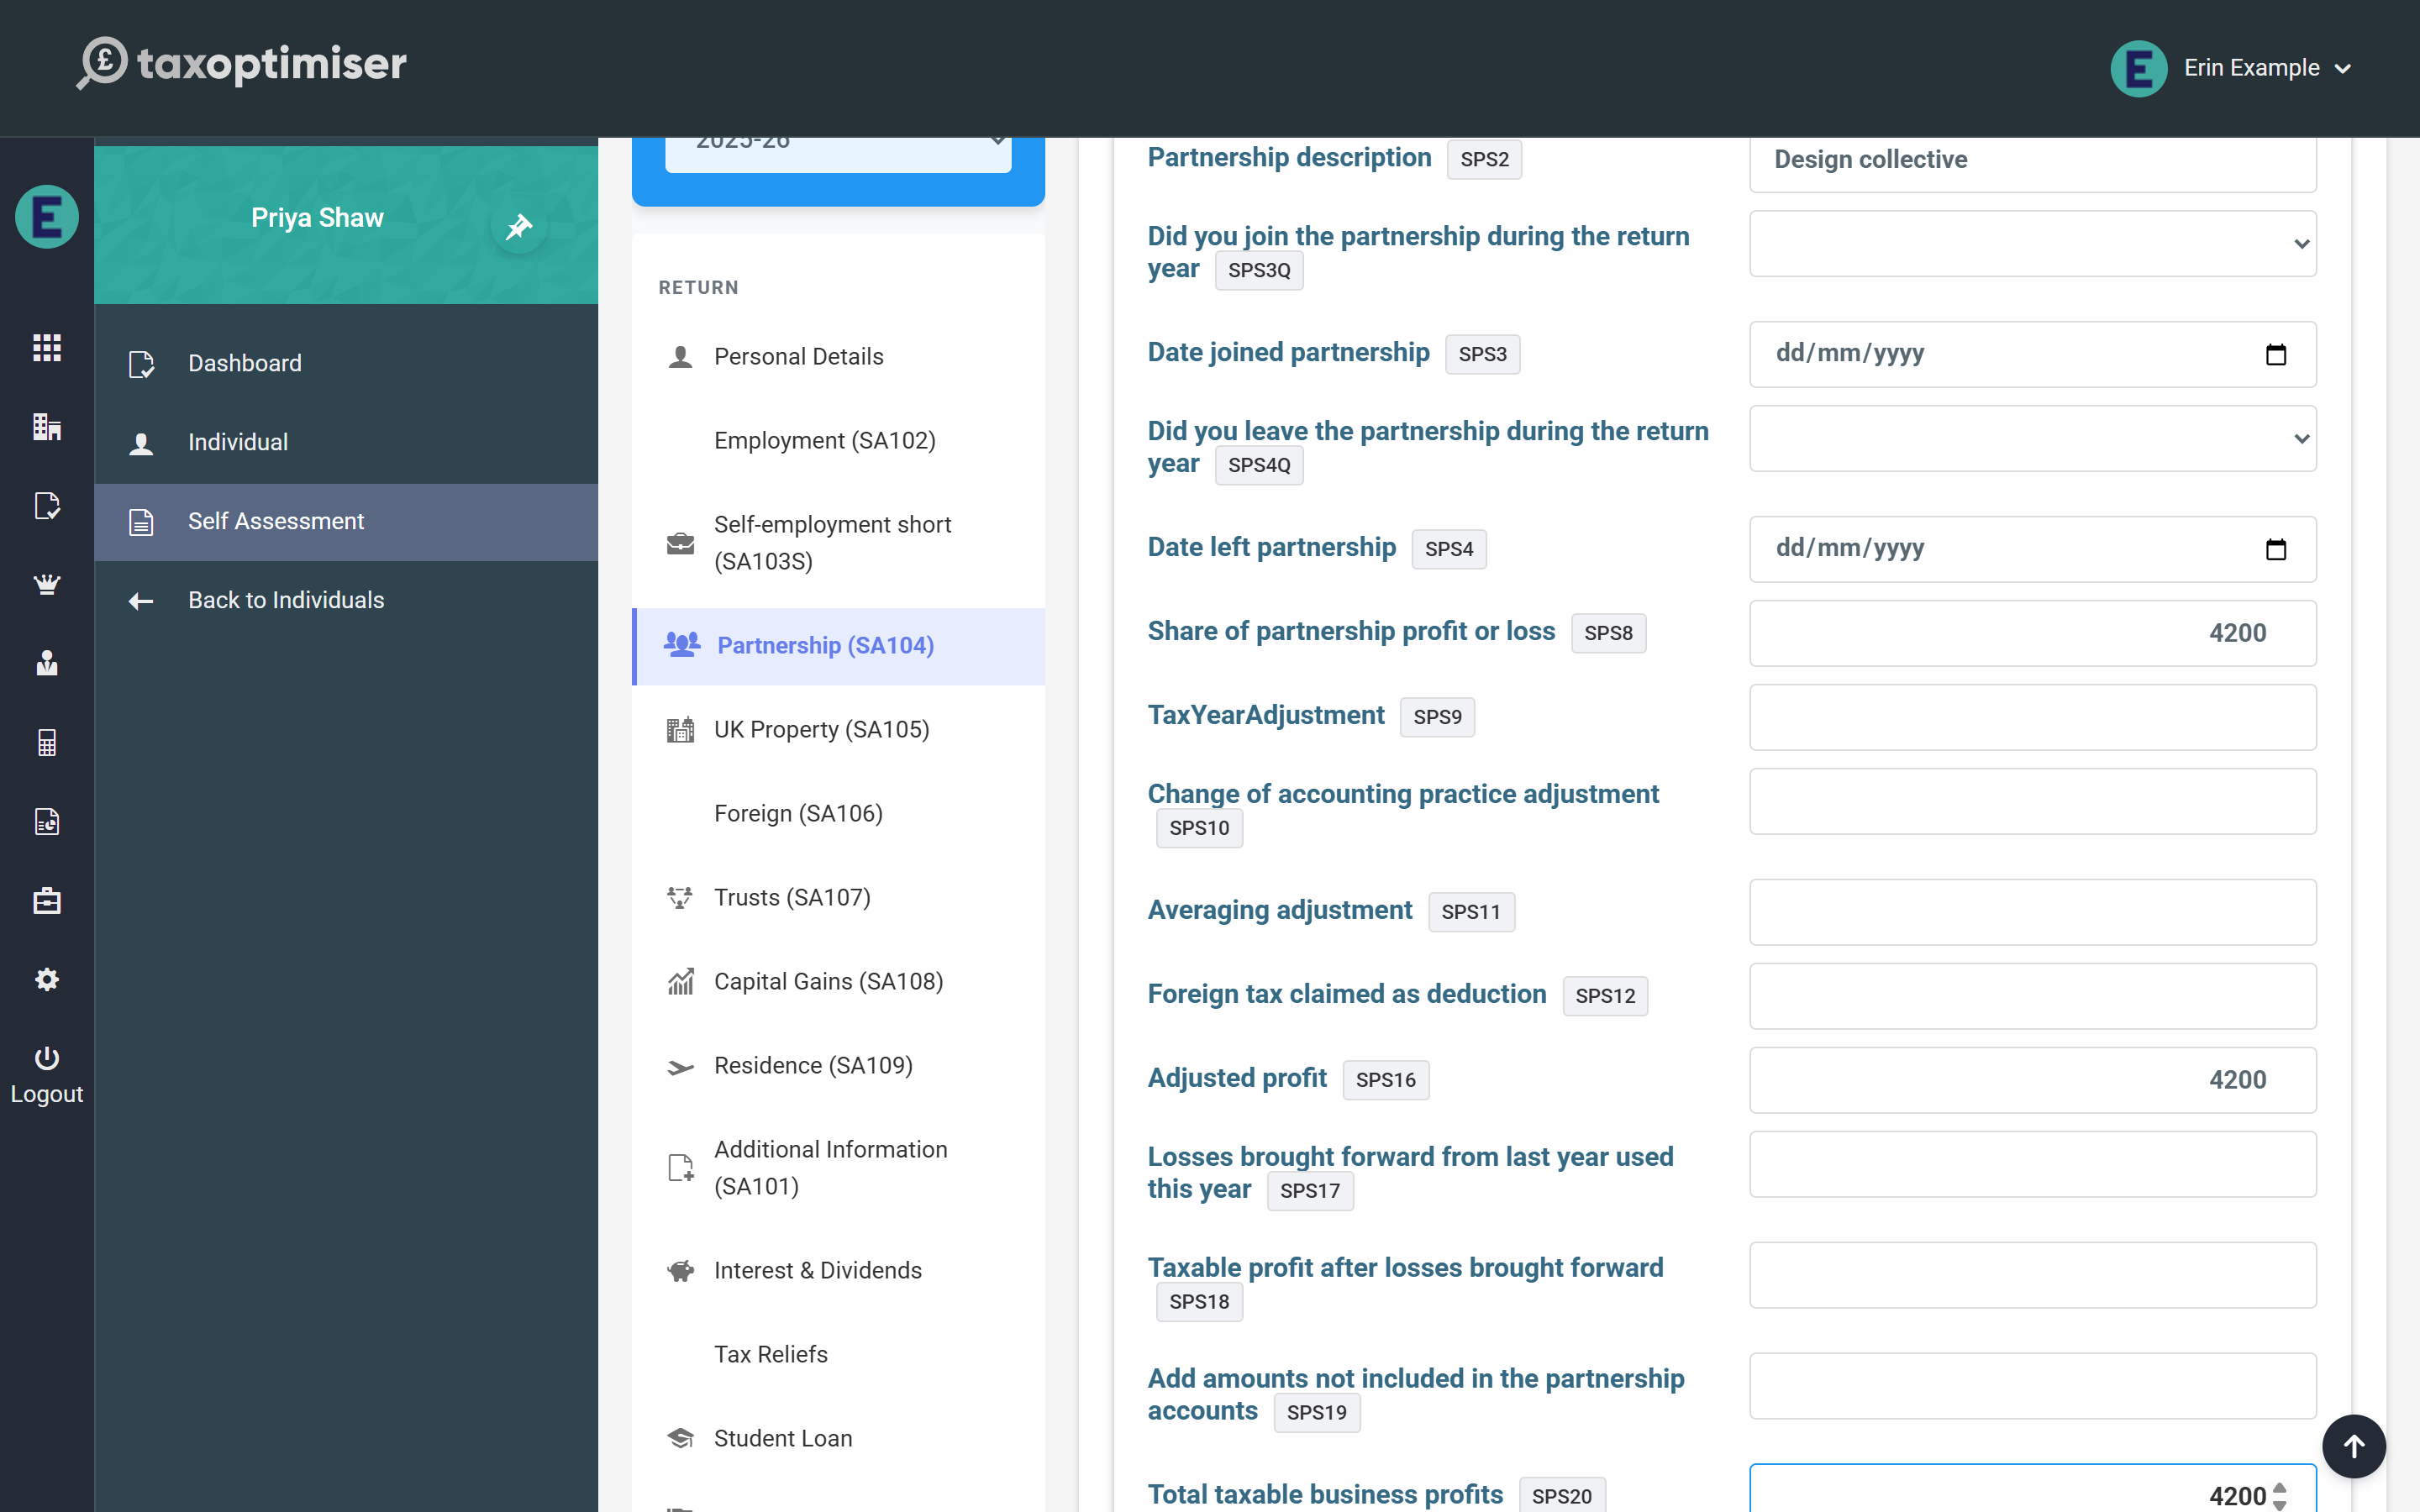
Partnership details
The partnership reference (UTR), the name and the joined / left in the year answers are required on every statement and carry a Required chip; the two questions default to No. The UTR is checked as you type against HMRC’s check-digit rule, and a join or leave date must fall inside the tax year with the leave date no earlier than the join. If your firm also prepares the partnership’s own SA800 in Tax Optimiser, the figures to key here are the ones on its Partnership Statement.
The share of profit, and the chain to the taxable figure
Enter the shares exactly as they appear on the statement. The calculation taxes the taxable profit box (20) alone, so a card with only the share of profit in box 8 would calculate nothing: the chain boxes — adjusted profit (16), the loss brought forward, taxable profit (20) and the loss to carry forward (21) — each show what the boxes feeding them come to with a Use this link, and the calculation adds a note with HMRC’s own figures whenever the chain does not add up. A loss share is entered as a negative figure in box 8. HMRC’s “zero when negative” boxes show nil rather than a negative total.

National Insurance
The profit share flows into Class 4 National Insurance. The exempt tick and the adjustment box (26 and 27) cannot both be used, and the exemption is one answer per person — a tick on any partnership or self-employment page exempts them all, as HMRC’s rules require. A client over State Pension age at the start of the year is exempt automatically, and the calculation says so. Voluntary Class 2 can be ticked here too: Tax Optimiser writes the amount into the Class 2 box, HMRC caps it at £219.95 across all trading and partnership pages, and rejects the voluntary tick where profits are already above the small profits threshold.
The full statement
The full page adds the client’s shares of untaxed and taxed interest, dividends, UK property, foreign and other income, and the tax deducted at partnership level, each with its own chain of adjustments. On the SA302 statement the partnership line shows the trading share; the interest and dividend shares are included in the return’s interest and dividend lines, so the income lines add up to total income. Unused residential finance costs from the partnership’s UK property or foreign property shares appear in the Carried forward table for next year’s boxes 41.2 and 63.2.
Transition profits
A transition profit spread on the full statement (box 16.3 and the amount treated as arising, 16.4) is taxed as HMRC taxes it: trading income of the year for the Personal Allowance taper, the band stack, student loans and Class 4, but left out of adjusted net income for the High Income Child Benefit Charge. See self-employment for the detail.
Next: Foreign (SA106).
